Sector Update / Consumer Discretionary / Click here for full PDF version
Author(s): Andrianto Saputra ; Nicholas Bryan
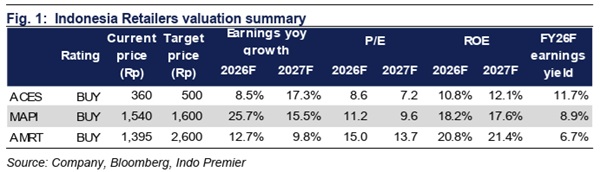
- 2Q26 aggregate SSSG stood at +2.0% yoy and this was driven by the active segment with SSSG of +6.5% yoy.
- We estimate retailers' opex-to-sales ratio to improve in 3Q26F amid favorable base effect and SSSG recovery.
- Maintain Neutral on the sector as we are still awaiting a more sustained SSSG recovery onwards.
Mixed 2Q26 result with as top performer
Aggregate 2Q26 retailers' sales grew by +7.7% yoy with aggregate SSSG of 2.0% yoy due to the shift in Lebaran. However, combined aggregate 1H26 retailers SSSG stood at +4.9% yoy, suggesting stronger Lebaran sales in FY26 than in FY25. We note that 2Q26 performance was dragged down by ' with SSSG of +0.1% yoy (vs. /AMRT's +3.3/+2.6% yoy). To note, 's 2Q26 SSSG of +3.3% yoy was driven by active segment with SSSG of +6.5% yoy, which we view as an indication of improving mid-income consumer purchasing power. Overall, 2Q26 's profit was above, while 's was in-line and ' below.
GPM trend to sustain in 2H26F
2Q26 GPM improved to 22.9% (+91bps yoy) as the company intentionally increased prices across F&B products despite no price increases from principals, alongside favourable changes in product mix. In addition, 2Q26 GPM rose to 48.5% (+186bps yoy), following 10% price increase in Apr26 to offset CNY/IDR depreciation of +13.4% yoy. Meanwhile, 's 2Q26 GPM remained stable at 41.1% (-14bps yoy), still above company FY26F guidance of 39-40%. Given a relatively stable 1H26 inventory days for /ACES at 132/275 (vs. 128/265 days in FY25), we expect GPM trend to be sustainable going into 2H. Moreover, expects its GPM improvement to be sustained despite tighter competition from Indomaret, as the company remains focused on protecting margin rather than sacrificing profitability for top-line growth through aggressive promotions.
We estimate retailers opex-to-sales ratio to improve in 3Q26F
Within our coverage, only recorded a flat 2Q26 opex-to-sales ratio of -3bps yoy, while /AMRT's increased by +235/+69bps yoy. We note a higher 2Q26 opex-to-sales ratio was due to higher freight costs from the impact of higher oil prices, while ' due to soft 2Q26 SSSG , resulting in negative operating leverage. Our channel check with listed minimart operator indicated that Jul26 performance was improving, as they saw a rebound in consumption. In addition, home improvement retailer also indicated that Jul26 performance was stable mom. Given a more favourable base effect for retailers (/MAPI/ACES's 3Q25 SSSG stood at +1.0/-5.0/-0.1% yoy), we expect opex-to-sales ratio to improve in 3Q26F.
Maintain Neutral
In terms of fund positioning, local funds are already well-positioned on the sector, except for as most funds participated in the mandatory tender offer (MTO) in Jul26. As such, the incremental buyers should come from foreign funds. Overall, we maintain our Neutral call for the sector as we still await for a stronger SSSG recovery. Our pecking order is as follows: >MAPI>.
Sumber : IPS