Company update / Telecommunications / IJ / Click here for full PDF version
Author(s): Aurelia Barus ; Belva Monica
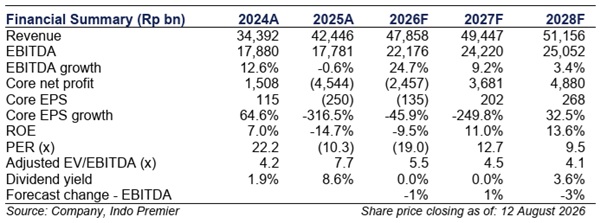
- 2Q26 EBITDA rose +3% qoq, bringing 1H26 EBITDA to Rp11tr (+25% yoy), in-line with ours but ahead of cons. EBIT turned +ve in 2Q26.
- Mobile ARPU declined slightly by -1% qoq, while subscribers remained stable, keeping mobile performance in-line.
- We revise FY26-28F EBITDA by -3% to +1%, now expecting 12% EBITDA CAGR FY25-28F. Retain BUY call.
2Q26 results: in-line with ours but above consensus; EBIT turned +ve
2Q26 EBITDA came at Rp5.6tr (+3% qoq), bringing 1H26 EBITDA to Rp11tr (+25% yoy), in-line with our FY26F (49%) but ahead of cons (52%; 3-year mean: 49%). 2Q26 revenue also rose +3% qoq, with 1H26 revenue at Rp24tr (+26% yoy), in-line. 2Q26 marked the first positive EBIT of Rp386bn since the merger. Core net loss narrowed to Rp392bn from Rp882bn in 1Q26 with 1H26 core net loss at Rp1.3tr.
Mobile ARPU slightly declined qoq, but still expect improvement ahead
2Q26 mobile ARPU declined 1% qoq to Rp46.9k vs. 1.8-2% qoq growth at peers. Management noted this was within expectation given the lack of festive momentum and still expects LT improvement. 1H26 ARPU stood at Rp47.1k (+24% yoy), in-line with our FY26F est. of Rp47.9k. We maintain our FY26F ARPU assumption, implying 3% hoh growth in 2H26F, while lowering FY27-28F ARPU growth to 4% yoy p.a from 8-9% previously.
Stable mobile subscribers, with potential upside from expansion
Mobile subscribers were stable qoq at 69.4mn in 2Q26 vs. 0.1-0.6% qoq declines at peers, and slightly above our FY26F estimate. While management remains focused on customer value over subscriber growth, expansion into new areas could drive growth ahead. We raise our FY26-28F assumptions and maintain a stable FY27-28F outlook. Faster subscriber growth offers upside to our estimates by 1-2% (see Fig. 3).
Lower integration costs, on track synergies, but higher capex for 5G
Management now targets lower FY26F integration costs of Rp300bn, while maintaining Rp4.5-5tr accelerated depreciation and US$250-300mn gross synergy savings. Integration and accelerated depreciation should largely complete by 3Q26F. Capex is now higher at Rp20tr (41% capex/revenue), up by Rp5tr from previous guidance of Rp15tr, mainly for 5G-related equipment upgrades and modernization.
Retain BUY call with a slightly higher TP of Rp5,300
We adjust FY26-28F EBITDA by -3% to +1%, pricing in higher mobile subscribers, new spectrum fee, higher capex, while lowering FY27-28F ARPU growth. Retain BUY call with a TP of Rp5,300 (8x 12M fwd EV/EBITDA). Completion of integration and monetization are the catalysts.
Sumber : IPS