MacroInsight / Click here for full PDF version
Author(s): Kefas Sidauruk
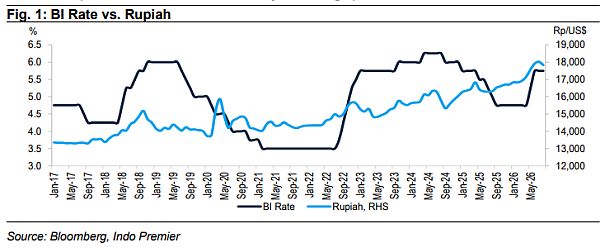
- We expect BI to hold policy rate at 5.75% on next week meeting as Rupiah remain stable. However, stronger US$ and rate hikes are the risk.
- Amid constrained fiscal room, monetary policy is likely to get looser through lower SRBI net issuance and macroprudential incentive.
- Rupiah depreciation risk shall remain contained despite external pressure and expansionary monetary policy.
BI to hold rate next week despite Fed/BoJ hike
We expect stronger fiscal-monetary synergy following the appointment of Suahasil as new Minister of Finance -- timely given the pivotal period for global central banks. The Fed and BoJ are expected to each hike rates by +25bps in the coming days. Historically, such moves would trigger a series of monetary tightening across EM including Indonesia, particularly on renewed inflationary pressure from higher oil prices. We expect BI to hold policy rate at next week meeting on three grounds: 1) Rupiah remains resilient MTD at +0.2% versus EM at -0.3%; 2) unchanged subsidized fuel (Pertalite) prices despite elevated oil, which shall offset food inflation in the near-term; and 3) BI has priced in one rate hike by the Fed during their 100bps of cumulative rate hikes in May-Jun26.
Monetary expansion to balance constrained fiscal space
Given constrained fiscal room to absorb higher oil prices, we think an expansionary monetary policy is now needed to support growth. Note that BI has shifted toward macroprudential incentives to offset the tightening effect of higher rate. The newly-introduced funding ratio incentive which offers a 2% RRR cut to banks that reduce their SRBI +SBN holdings to below 19% of third party funding, aimed at channelling liquidity into lending. Notably, banks have continued as net buyers of INDOGB in Sep26 (+Rp11tr MTD / +Rp84tr QTD). On that note, SRBI net issuance (on 3-months rolling basis) has turned negative for the first time since Nov25, implying ongoing reduction in SRBI outstanding. In service of fiscal-monetary synergy, we expect BI to continue loosening monetary operations while remaining a standby buyer for INDOGB should selling pressure arise from the banks
Rupiah depreciation risk should remain contained
As monetary conditions could ease further in the near term, several factors should limit Rupiah depreciation despite the challenging external backdrop: 1) Indonesia's short-term real yield sits at +140bps above the EM average (3.6% vs. 2.2%), providing attractive carry with lower fiscal risk (Suahasil has reaffirmed the -3% deficit commitment); 2) resilient coal and CPO exports partially offset the deficit pressure from higher oil prices; and 3) stabilizing FX reserves (+US$1.5bn since the May26 trough).
Sumber : IPS