Company Update / Telecommunications / IJ / Click here for full PDF version
A uthor(s): Aurelia Barus ; Belva Monica
- and Ooredoo Group launched Zankore, a dedicated AI computing and neocloud platform, with NVIDIA & Nokia, targeting 1GW capacity.
- We estimate a project IRR of 12-13% and an equity payback period of <3 years.
- We expect the project to be earnings accretive; retain BUY call.
Announcement of Zankore establishment
On 6th Aug 2026, and Ooredoo Group announced ZanKore, a dedicated AI computing and neocloud platform in partnership with NVIDIA and Nokia. The project targets 1GW of NVIDIA DSX AI Factory capacity, with the initial 200MW phase scheduled to commence operations in 1H27 using NVIDIA GB300 NVL72 systems with NVIDIA DSX MaxLPS, which is designed to deliver up to 40% more compute within the same power budget. Ooredoo will invest US$800mn for a 49% stake, while the remaining 51% will be held by , NVIDIA, and Nokia.
Project IRR estimates at the range of 12-13%
Based on management's disclosure, Zankore aims to generate cumulative revenue/EBITDA of US$13bn/US$9bn over five years. This implies annual revenue of c.US$13mn/MW, in the range of global AI cloud peers at around US$10-15mn/MW. Assuming development capex of US$20mn-25mn/MW, we estimate total capex for the initial 200MW phase at US$4bn-5bn. Against an implied equity investment of US$1.6bn (100% basis), this suggests project debt of c.US$2.4bn-3.4bn. Assuming annual revenue of US$10mn-13mn/MW and a 69% EBITDA margin, we estimate the project could generate an IRR of 12%-13%, with an equity payback period of less than three years (Figs. 1 & 4).
The project shall be earnings accretive for
Based on our discussion with , we expect the company to hold the largest share of the remaining 51% stake. Assuming a 20-30% stake in Zankore, we estimate an equity investment of US$327-490mn and attributable annual net profit of US$64-131mn (Figs. 1-4). Assuming 70% debt financing for the equity injection, the project could still deliver 11-29% upside to our FY27-28F core NP forecasts.
Retain our BUY call
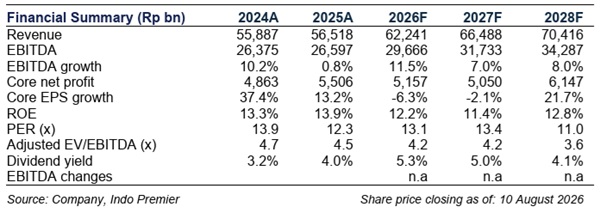
Zankore eliminates the need for to invest directly in GPU infrastructure from FY27F, reducing execution risk and upfront capex. Successful execution could also drive a valuation re-rating, as AI cloud business typically trade at significantly higher EV/EBITDA multiples than traditional telecom operators. We have yet to include these in our forecasts, pending further details. However, we view this to be positive for now.
Sumber : IPS
powered by: IPOTNEWS.COM