Company Update / IJ / Click here for full PDF version
Author(s): Ryan Winipta - +62 21 5088 7168 ext. 718
- We think majority of downsides for which include soft 3Q26F NP on lower gold volume and decline in nickel ore ASP are largely priced-in.
- We think downside to nickel ore price is limited; concurrently, shall benefit from rising gold price.
- We maintain our Buy rating with Rp3,700 TP as become a viable gold proxy with potential upside to gold trading margin.
Gold remains as inflation hedge; nickel has more balanced S&D
We remain bullish on gold as an inflation hedge. Higher gasoline and diesel prices could add to inflationary pressure, given the elevated diesel crack spread (US$108/bbl) and ongoing supply disruption in the Strait of Hormuz. We also read the recent spike in the US 10-year Treasury yield to ~5% as a sign of eroding investor confidence in the US Treasuries rather than as a sign of tighter monetary policy. This should drive continued rotation out of UST into alternative store of value such as gold. On nickel, we remain bearish as ore supply and demand have become more balanced, as shown by the sharp narrowing of the ore premium to HPM (Fig. 2). That said, we see limited further downside to ore prices as HPM should act as a price floor, in our view.
Downsides are largely priced-in with potential turnaround in 4Q26F
We think most of the downside for is already reflected in the share price. Investors appear well aware of a likely qoq decline in 3Q26F net profit, driven by lower gold volume in Jul-Aug and weaker ore prices. This is visible in 's share price underperformance vs. gold peers during August's gold rally from US$4.0k/oz to US$4.6k/oz ( +16% vs. +48%; +31%; +52%). Management also indicated that gold trading volume has begun to recover in September, which opens the possibility of a turnaround in 4Q26F. We expect 3Q26F net profit of Rp2.0-2.2tr (-26% to -33% qoq) or 9M26F of Rp8.4-8.6tr, equivalent to 80-82% of consensus FY26F.
Maintain Buy with an unchanged TP of Rp3,700/share
We maintain our Buy rating and Rp3,700 TP (+17% upside). With most of the downsides have been priced in, we think 's share price should increasingly track gold, making it a viable gold proxy. We also see potential upside to gold trading margin (2Q26: 4%; 1Q26 peak: 10%), as lower import volume reflect greater supply from domestic gold miners. Downside risks: lower gold price, weaker gold retail demand, lower-than-expected nickel ore production, and regulatory changes to HPM or RKAB quotas.
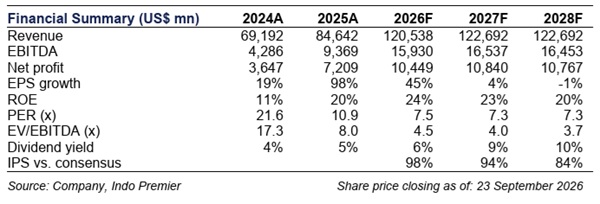
Sumber : IPS