Sector Update / Banks / Click here for full PDF version
Author(s): Jovent Muliadi ; Shierly Elizabeth
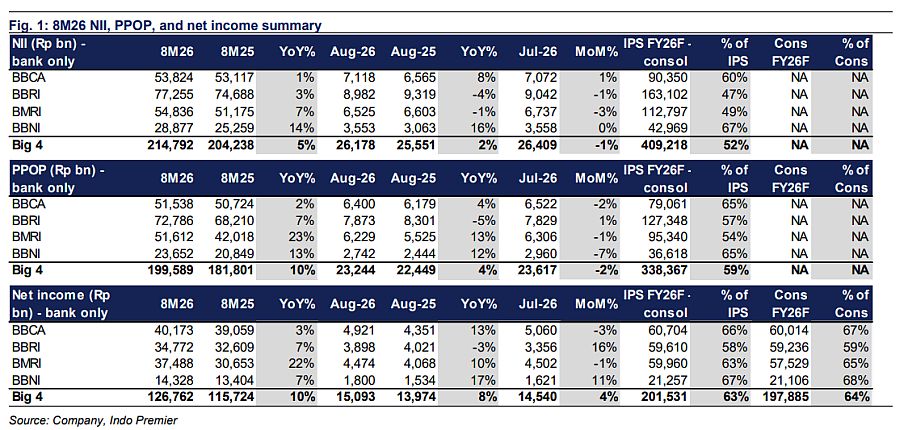
- Aggregate big 4 bank-only profit of Rp126.8tr in 8M26 (+10% yoy) came in-line. and led the PPOP growth at +23/13% yoy.
- Big 4 bank-only NIM softened to 4.9% in 8M26 (-35bp yoy) on lower asset yield (-52bp yoy), though CoF has improved by -22bp yoy.
- We expect loan repricing to gradually take effect in Jul-Dec to offset NIM pressure. and remained our top picks.
8M26 bank-only results: in-line; strong PPOP from and
Aggregate big 4 bank-only earnings grew +10% yoy to Rp126.8tr in 8M26 (+4% mom), still in-line with our/cons FY26F consol estimates of +6%/4%. led earnings growth (+22% yoy), while other banks grew +3% to +7% yoy. In terms of PPOP , was the strongest at +23% yoy, followed by at +13% yoy. NIM fell -35bp yoy to 4.9% on lower asset yield (-52bp yoy) despite CoF improvement (-22bp yoy). Loan grew +17% yoy, while deposit increased +16% yoy, translating to LDR of 88% vs. 87% in 8M25.
: in-line on decent non-II and lower provisions
's bank-only net profit of Rp40.2tr in 8M26 (+3% yoy/-3% mom) came in-line with our/cons FY26F consol estimates at 66%/67%. PPOP grew +2% yoy, supported by stronger non-II (+3% yoy) despite softer NII (+1% yoy) and higher opex (+4% yoy). Provisions fell -19% yoy (-2% mom), bringing CoC to 0.3% (-12bp yoy/flat mom), below guidance of 0.4-0.5%. NIM fell to 5.6% (-31bp yoy) on lower asset yield (-28bp yoy) and slightly higher CoF (+2bp yoy). Loan grew +11% yoy vs. deposit at +8% yoy. LDR at 81% vs. 79% in 8M25.
: in-line; bank-only CoC still a tad higher than guidance
bank-only net profit of Rp34.7tr in 8M26 (+7% yoy/+16% mom) was in-line with our/cons FY26F consol estimates at 67%. PPOP grew +7% yoy, driven by NII (+3% yoy) and non-II (+4% yoy), along with lower opex (-3% yoy). Provision rose +9% yoy (-14% mom), lifting CoC to 3.3% (-3bp yoy/-9bp mom), above guidance of 2.9-3.2%. NIM stood at 6.2% (-39bp yoy) on lower asset yield (-86bp yoy) despite better CoF (-53bp yoy). Loan grew +14% yoy vs. deposit at +13% yoy, resulting in stable yoy LDR at 87%.
: above consensus amid strong PPOP
bank-only net profit of Rp37.5tr in 8M26 (+22% yoy/-1% mom) came above our/consensus FY26F consol estimates at 67%/70% on the back of robust PPOP at +23% yoy. Provision rose by +24% yoy (-4% mom), bringing CoC to 0.6% (+4bp yoy/flat mom), within guidance of 0.6-0.8%. NIM dropped to 4.1% (-33bp yoy), as the decline in loan yield (-55bp yoy) outweighed the improvement in CoF (-28bp yoy). Both loan and deposit grew +18% yoy, with LDR remained stable yoy at 94%.
: in-line on robust PPOP , while CoC remained within guidance
bank-only net profit of Rp14.3tr in 8M26 (+7% yoy/+11% mom) was in-line with our/cons FY26F consol estimates 67%/68%. PPOP remained robust (+13% yoy), driven by strong NII (+14% yoy) and non-II (+11% yoy). Provision rose by +27% yoy (-19% mom), bringing CoC to 1.0% (+7bp yoy/-6bp mom), in-line with guidance of 1.0-1.2%. NIM softened to 3.5% (-15bp yoy) on weaker asset yield (-12bp yoy) despite a slight improvement in CoF (-2bp yoy). Loan grew +27% yoy while deposit rose +29% yoy, resulting in lower LDR of 87% vs. 88% in 8M25.
Sumber : IPS