Sector Update / Consumer Staples / Click here for full PDF version
Author(s): Andrianto Saputra ; Nicholas Bryan
- We expect El-Nino to pressure staples' GPM in 1H27F and may only start to recover in 2H27F.
- is the most negatively affected by El-Nino, while is the least impacted.
- Maintain Overweight for the sector with our top pick is .
El Nino may pressure staples GPM in 1H27F
BMKG forecasted a very strong El-Nino developing from Jun26, with the intensity expected to peak in Dec26-Jan27 and potentially reach levels similar to Nov15-Jan16 El-Nino. Historically, El-Nino has adversely affected CPO, coffee, cocoa and sugar crops, leading to lower production and higher soft commodity prices, with most soft commodities (coffee/cocoa/sugar) production typically taking 6-12 months to recover after an El-Nino event. As such, we expect staples companies to face cost pressures throughout 1H27F, with GPM possibly starting to recover in 2H27F.
El-Nino may negatively impact
We assess the potential impact of El-Nino on staples companies. Among our coverage, /ICBP/UNVR/CMRY have exposure to these raw materials, which account for 36/19/10/5% of their COGS . Assuming no pass-through of higher input costs, our sensitivity analysis shows that a 5% increase in the prices of coffee, sugar, cocoa, and CPO would reduce FY27F net profit for /ICBP/UNVR/CMRY by -11.7/-3.8/-1.6/-0.6% (Fig. 18).
We expect 1H27F price hikes to be less aggressive than in FY22
Our conversation with staples companies, suggested that they intend to fully pass on higher input costs. In addition, also aims to reduce distributor inventory days, as it expects to pass on higher costs through regrammage (reformulate product) with a shorter lag. However, we see a risk to sales volume if raw material prices increase significantly. Historically, domestic aggregate revenue growth slowed to +1.2% yoy in FY23 (vs. +10% yoy in FY22), following the massive price hikes in FY22 (average: +16% yoy) amid cost pressure (Fig. 3). Given the relatively healthy 1H26 GPM reported by staples companies, with GPM profiles are in-line with respective companies' guidance (Fig. 2), we view ASP hikes may not be as significant vs. FY22, when the 1H22 GPM (-419bps yoy) was under bigger pressure.
is less impacted from El-Nino event
Within our coverage, is one of the staples companies that wasn't negatively impacted from El-Nino as 65% of 's raw material comes from oil-related (API and packaging). According to our conversation with management, API prices have yet to increase materially beyond the hike already seen in 2Q26, suggesting GPM profile should stay close to 2Q26's.
Maintain OW with as our top pick
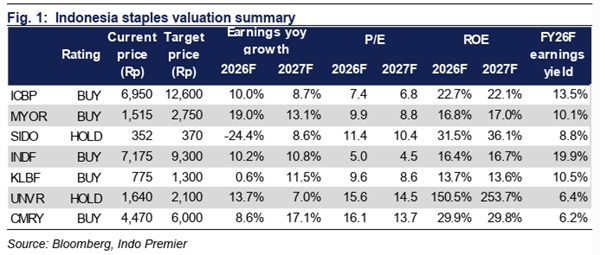
In terms of fund positioning, local funds are already well positioned for the sector; thus, the incremental buyers should come from foreign funds. We note that the sector is traded at 9.5x FY26F PE (-2.0 s.d. from its 5yr mean), reaching below Covid level, suggesting the sector provides a better risk- reward. In sum, we maintain OW rating for the sector with pecking order of: >CMRY>>MYOR>>SIDO. Risks to our call: prolonged higher raw material prices and soft purchasing power.
Sumber : IPS