Wall Street steadied Friday, halting the S&P 500's four-day slide as a pullback in oil eased some inflation anxiety -- S&P 500 rose +0.9%, Nasdaq 100 rose +0.9%, Brent crude fell -2.8% to $104.6 a barrel Friday (11/09).
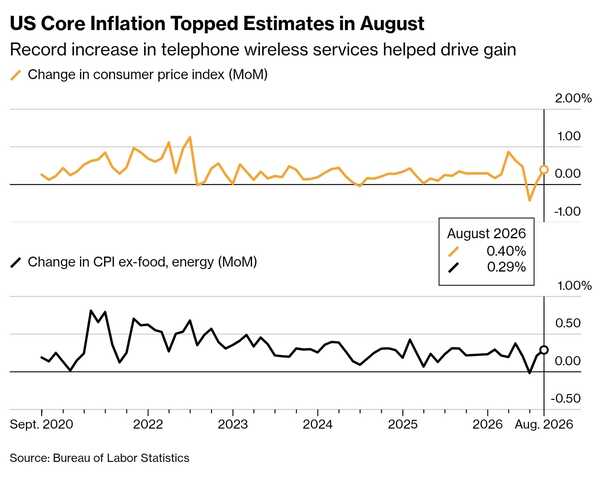
> US Core CPI rose 0.3% mom in August (higher than 0.2% estimated), suggesting inflation made little real progress last month amid ongoing pressure from the Iran war, tariffs, and the AI data center buildout.
US equity futures fell this morning, as oil advanced & investors weighed renewed concerns over the pace of AI development -- Anthropic CEO Dario Amodei called for the industry to slow development of its most advanced models, proposing independent third-party safety evaluations with OpenAI's Sam Altman and xAI's Elon Musk both publicly backing the call.
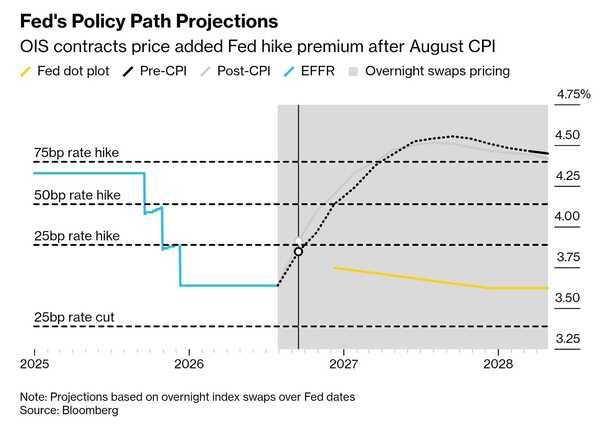
The probability of a September Fed hike jumped to around 90%, up from ~70% just a day earlier following CPI released, with investors also now pricing a second hike by December.
Interestingly, economists' views sharply diverge from investors' positioning -- a majority of economists actually expect the Fed to hold steady through 2027, citing tempering inflation and midterm election proximity.
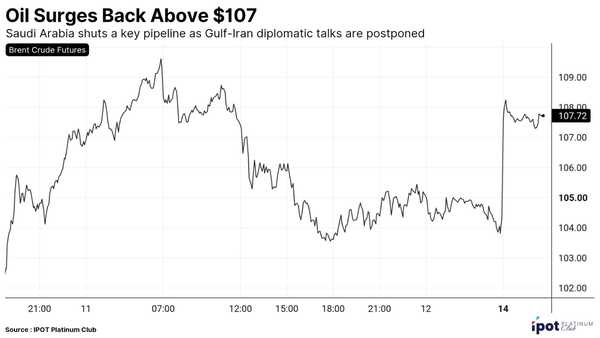
Oil Surges with Brent rose +2.8% toward $107 this morning, extending last week's nearly 9% rally; WTI traded near $102
- Saudi Arabia shut its East-West pipeline -- a critical route used to bypass the Strait of Hormuz during the conflict -- following fresh attacks, deepening the global energy crunch with no indication yet of when operations will resume.
- Meanwhile, a planned Monday meeting between Iran and Gulf nations on establishing a temporary Hormuz shipping lane was postponed.
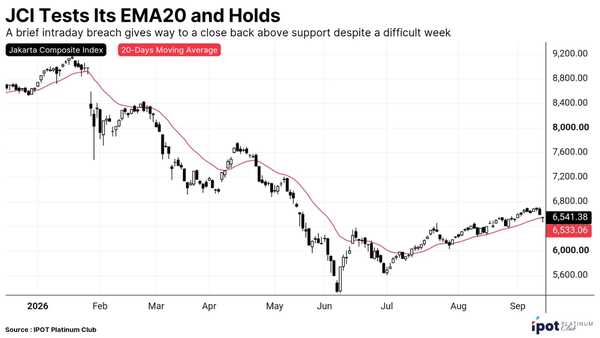
The JCI fell -0.73% to 6,541 Friday, swinging between 6,462 and 6,552 intraday -- while the session low briefly breached the EMA20 technical support, the index closed back above it-- surging in Oil prices and rising rate hike expectation trigger risk-off sentiment.
> The weekly picture shows the scale of the pullback in context: JCI fell -1.4% over the week to 6,541.38, giving back some of the prior week's +1.82% gain that had taken the index to a four-month high ad Foreign flows reversed too -- Rp3.36 trillion in net selling this week, versus Rp2.3 trillion in net buying the week before.
o
Confirmed plans to list two subsidiaries on the IDX in 2027 -- delayed from an original 2025 target -- while preparing ~$150 million for its first three pipeline projects, including a floating LNG facility. Management was candid that timing remains subject to capital market conditions, a sensible, flexible approach given the environment.
o
Aneka Tambang set Rp6 trillion in capital expenditure for 2026, weighted toward gold and EV battery value chains, with five downstreaming projects underway across gold, nickel, and bauxite alongside strategic partners. Management emphasized a gradual realization approach to ensure sustainable growth.
o
State builder PT PP signed a restructuring agreement with Mandiri, BRI, BNI, and covering Rp18.2 trillion (~$1 billion) in debt -- Rp13.3 trillion repaid over 15 years, Rp4 trillion over five years via asset sales, with accrued interest settled over 18 months. This adds to Danantara's growing workload cleaning up distressed state-owned companies -- PP's cash position more than halved to Rp1.2 trillion by June, against nearly Rp5.8 trillion due within a year.
Corporate Calendar
14/09: RUPS : , ,
15/09: Cash Dividend Cumdate: ,
RUPS : , ,
16/09: Right Issue Cumdate:
RUPS :
17/09: RUPS : , , ,
18/09: RUPS : , , ,
Economic Calendar
CN - New Loans (Aug)
Disclaimer On
IPOT Platinum Club
Sumber : IPS