Wall Street traders refrained from making riskier bets in the countdown to the Federal Reserve decision, with stocks falling as elevated oil prices drove bond yields to multi-year highs.
- The 10-year Treasury yield touched 5.04% Tuesday -- its highest in nearly two decades -- before settling at 5.00%.
- A weak $13 billion 20-year bond auction added to the pressure, extending declines in longer-dated Treasuries.
- Almost 350 S&P 500 constituents retreated; S&P 500 -0.45%, Nasdaq -0.6%
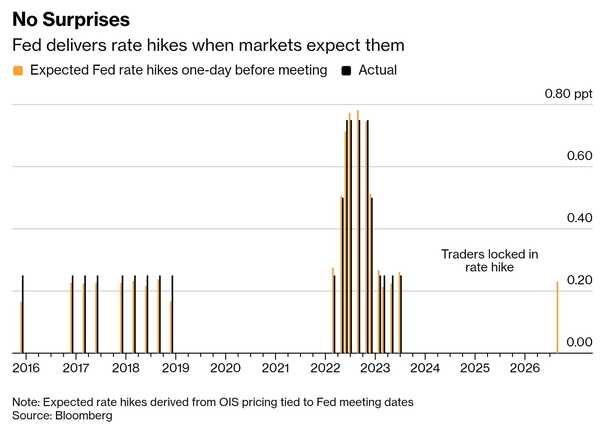
Bond traders pricing a 94% chance of a FED quarter-point hike -- and historically, when expectations reach that level, the Fed has always delivered, dating back to 2008 -- The debate has shifted from 'if' to 'how much' tightening this cycle will require to restore price stability as a one-and-done hiking approach is unlikely. Three big central banks have meetings this week --the Fed tonight, then the UK and Japan-- and they're all expected to hike rates.
On Commodities:
- Brent settled near $109 -- up almost +3% -- before pairing its gain to below $108 in Asia Trade as outages at a key Saudi pipeline and Libyan oil fields compounded losses already stemming from the Iran war. Saudi Aramco has reportedly begun delaying oil supplies to some European customers this month
- Gold edged higher to just above $4,300 but remains down about 3% in September after peaking above $4,700 in late August -- the metal caught in the same push-pull between inflation fear and rate-hike conviction we've tracked all month.
- Copper rose +0.6% on Tuesday to settle at `$14,083.50 a metric ton as Economic data from China showed industrial output in the world's biggest metals consumer improved more than expected in August
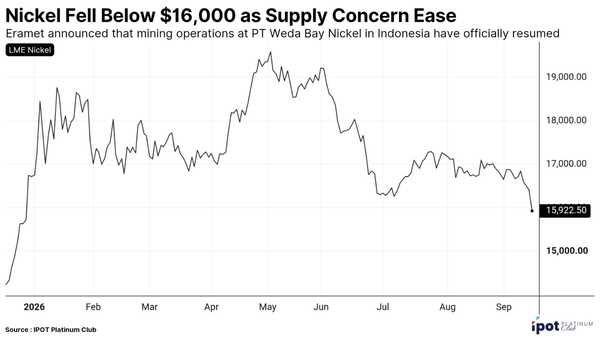
- Nickel prices have dropped for four consecutive days, falling -5.8% to $15,897 per ton after Eramet announced that mining operations at PT Weda Bay Nickel in Indonesia have officially resumed, easing supply concerns.
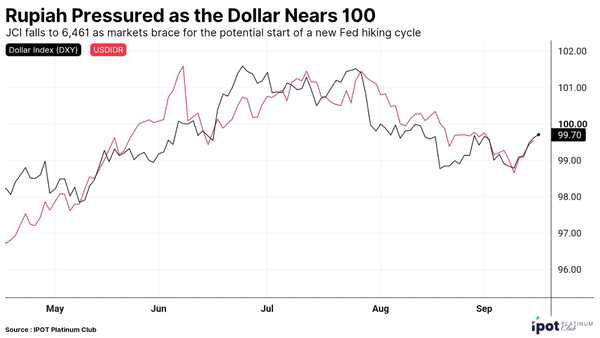
The JCI fell -1.13% to 6,461 Tuesday, as surging oil, rising global borrowing costs, and a broadly cautious wait-and-see posture ahead of tonight's Fed decision weighed on sentiment. The Rupiah weakened further to Rp17,694, as the Dollar Index continued strengthening toward the 100 level.
o S&P Warns at Indonesian State Lenders
State-owned banks (Mandiri, BRI, BNI) have seen loan growth surge to 26% YoY -- more than double the industry's 12% pace -- driven largely by government and SOE-directed lending that has exceeded both S&P's forecasts and the banks' own guidance. S&P expects NIM to fall 10-20bps over the next 12-18 months as this lower-yielding growth continues, though it also expects loan growth to moderate to 8-10% as liquidity tightens -- with healthy capitalization providing a buffer.
o Fuel Prices
Despite crude oil averaging $85-90/barrel this year -- well above the $70 budget assumption -- Energy Minister Bahlil confirmed subsidized fuel prices will stay unchanged through end-2026. This is a real fiscal cost being absorbed to protect consumers, and worth watching for how it interacts with the sub-3% deficit commitment new Finance Minister Nazara has pledged to maintain.
o External Debt
Indonesia's external debt remained well-controlled at $454.8 billion (30.7% of GDP), up modestly from the prior month, with long-term borrowing still dominating the total.
o
Kalbe Farma will conduct a share buyback of up to Rp500 billion over three months (September 16 - December 16).
o x
Chandra Asri Pacific signed an MoU with Bank Mandiri to provide payment collection, banking transactions, and financial support tailored to 's petrochemical customer partners.
o
Dharma Polimetal's joint venture with Minth Group continues operational preparations, with the facility targeted to begin producing EV components in Q2 2027.
o
Pefindo affirmed Petrosea's idA+ rating (and idA+(sy) for its Sukuk Ijarah), citing business diversification as a support factor, though constrained by its debt risk profile.
Corporate Calendar
16/09: RUPS :
17/09: RUPS : , , ,
18/09: RUPS : , , ,
21/09: Right Issue Cumdate:
RUPS : ,
22/09: Right Issue Cumdate:
RUPS : , , ,
Economic Calendar
1. US - Core Retail Sales (MoM) (Aug)
2. US - Retail Sales (MoM) (Aug)
3. US - Retail Control (MoM) (Aug)
4. US - Export Price Index (MoM) (Aug)
5. US - Import Price Index (MoM) (Aug)
6. US - Retail Inventories Ex Auto (Jul)
7. US - Business Inventories (MoM) (Jul)
8. US - Crude Oil Inventories
9. US - Atlanta Fed GDPN ow (Q3)
10. US - Fed Interest Rate Decision
11. US - FOMC Economic Projections
12. US - FOMC Statement
13. US - Interest Rate Projection - 3rd Yr (Q1)
14. US - Interest Rate Projection - Current (Q3)
15. US - Interest Rate Projection - 2nd Yr (Q3)
16. US - Interest Rate Projection - Longer (Q3)
17. US - Interest Rate Projection - 1st Yr (Q3)
18. US - FOMC Press Conference
19. US - TIC Net Long-Term Transactions (Jul)
Suspensions
Opened :
Suspended :
Watchlist / FCA
In :
Out :
UMA
-
Disclaimer On
IPOT Platinum Club
Sumber : IPS