Non-rated / Utilities / IJ / Click here for full PDF version
A uthor(s): Aurelia Barus ; Belva Monica
- 2H26F revenue is expected to recover as gas supply issues were fully resolved in Apr26, with normalization will be reflected from 3Q26F.
- Data center contracted supply grew 23% yoy in 1H26F, with a 25% CAGR in FY25-30F, while further upside from additional inquiries.
- If demand exceeds expectations, the company is well positioned to expand, supported by a healthy balance sheet and strong cash position.
A better 2H26F outlook as gas supply fully recovered
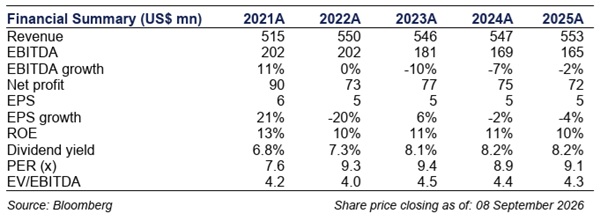
In 1H26, revenue reached US$275mn (1.3% yoy), with industrial customers growing 7.8% yoy, while PLN declined 37.4% yoy. The decline in PLN sales was due to gas supply issues that emerged in 2H25. Gas supply has since gradually recovered, with had resolved by end of FY25 and Pertamina EP expected to fully recover by Apr26. Hence, management expects stronger 2H26F performance, supported by a low 2H25 base and a full normalized gas supply in 2H26F. 1H26 EBITDA was US$96.3mn (+7% yoy), while core NP reached US$37.1mn (-6.3% yoy).
Robust data center demand with potential upside
Strong industrial demand growth in 1H26 was largely driven by data centers, which accounted for c.60% of the increase. As of 1H26, contracted data center capacity reached 274MW, up 47MW from the end of 2025, representing 12% of total industrial customers' consumption. targets 303MW by FY26F, increasing to 385MW in FY27F (+27% yoy) and potentially 447MW by FY30F, implying 25% CAGR in FY25-30F. If achieved, data centers would account for 20% of total industrial customers' consumption by FY30F. Our discussion with management suggests further upside to current targets, as data center inquiries continue to rise.
Well positioned for expansion
Our discussion with the company suggests that it can expand capacity if data center's demand exceeds the current capacity. Management remains more inclined toward gas engine power plant expansion if needed. It also has undeveloped land available across its three operating locations (Babelan, Jabadeka, MM-2100). As of 1H26, debt stood at US$343mn, with net gearing of 0.3x, with cash balance of US$124mn and investments US$174mn, providing ample funding capacity for expansion.
Consistent dividend payout outlook
In 2020-25, it maintained a DPR of 73-96% and continues to guide for an unchanged 60% DPR. It currently trades at 11.2x P/E, at +1 std. above LT mean.
Sumber : IPS